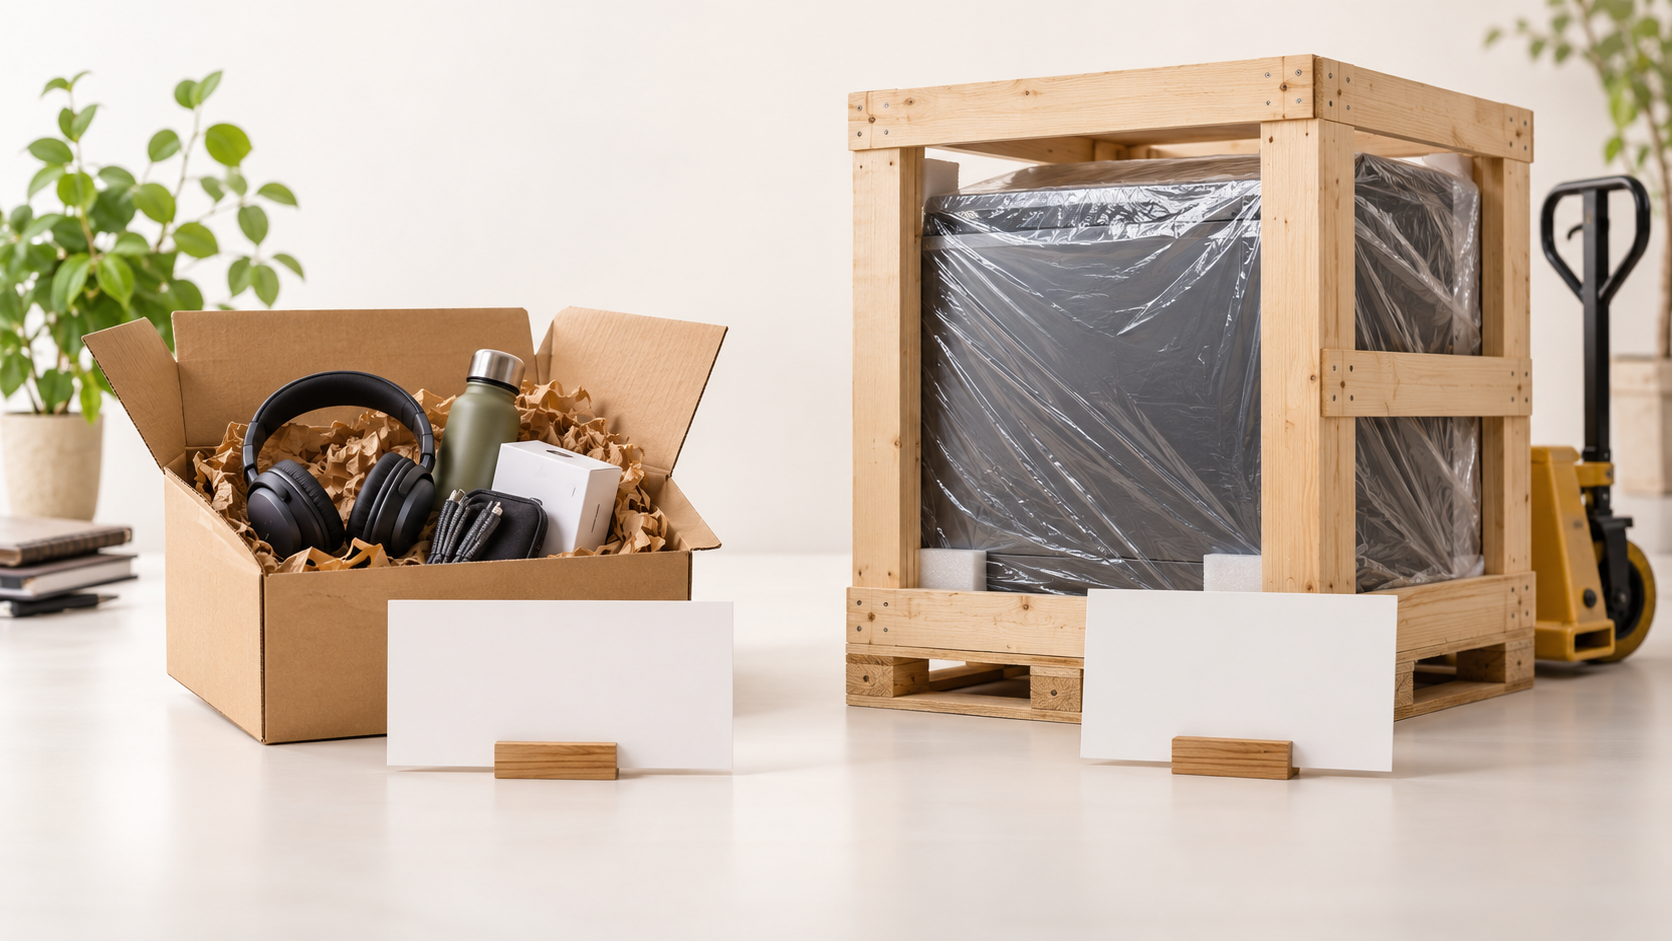
Two campaigns each generate the same amount of order revenue. One sells mostly small accessories; the other sells large products that require specialist delivery. Their headline revenue is equal, but the work and costs behind it are different.
A revenue target is useful when it sits beside an understanding of what was sold. Without that context, a campaign can reach the number while shifting demand towards a mix the business did not intend to prioritise.
Start with a commercial view the business recognises
Agree which costs and adjustments belong in the review. Product cost, fulfilment, discounts and later returns may affect the contribution of an order. Use the business's maintained figures and definitions rather than guessing from the catalogue price.
For a simple illustration, two orders priced at £100 can leave different amounts after their direct costs. The example explains why revenue alone is incomplete; it is not a substitute for the retailer's actual accounting.
State whether figures are preliminary or settled. A recent order may still produce a cancellation or return, and some costs may be updated later.
Group products by a useful trading question
The grouping could follow range, contribution band, fulfilment requirement or strategic purpose. Choose a view that informs the decision being made.
A campaign intended to introduce a new range should not be evaluated as though every product in the account serves that purpose. Conversely, a broad sales campaign may need a view of the overall mix rather than isolated enthusiasm for its strongest item.
Keep the groups stable enough to compare, and explain any change to the catalogue or classification.
Review availability and the next increment
Strong historical sales do not guarantee that more of the same range can be supplied profitably. Stock, delivery capacity and promotional terms can change the next decision.
Before expanding activity, ask which products are likely to absorb additional demand and whether the commercial conditions remain suitable. A high-revenue item with constrained fulfilment may need a different pace from a well stocked accessory range.
An illustrative comparison of two order mixes
Consider a simplified example in which two groups of orders each generate £1,000 of revenue. These figures are invented to explain the review; they are not a model of a particular retailer.
| Item in the simplified review | Group A | Group B |
|---|---|---|
| Order revenue | £1,000 | £1,000 |
| Product and direct fulfilment costs | £550 | £750 |
| Amount before advertising and other costs | £450 | £250 |
| Advertising cost assigned in this example | £150 | £150 |
| Amount after those listed costs | £300 | £100 |
The two groups have the same revenue and advertising cost, but different amounts remain after the costs included here. The table deliberately leaves out other business costs, later adjustments and uncertainty about assigning advertising credit. It illustrates the product-mix question rather than claiming to calculate final profit.
The next review should ask why the direct costs differ. Group B might contain bulky items with a higher delivery requirement, heavily discounted products or a different range. Each explanation suggests a different trading conversation.
If the business wants to prioritise Group B for a strategic reason, the lower amount may be acceptable under its plan. Marketing should carry that reason into the objective instead of accidentally discovering the difference after the revenue target has been celebrated.
Include the orders that change later
Recent figures can still move. An order may be cancelled, a return may arrive or a fulfilment adjustment may become known. Use the accounting approach agreed by the business, with the status of the report clearly stated.
Where settled and recent groups are shown together, mark the difference. A preliminary result can inform current monitoring, while a later review provides a more complete commercial account. Do not compare them as though both have passed through the same process.
The mix can also change within a product family. An accessory bundle, a discounted variant and a standard full-price item may share a category while creating different order economics. Choose enough detail to support the decision without making the report impossible to maintain.
Ask what the next budget would buy
Historical mix is a starting point. The next increment of activity might reach different customers, promote a different range or run while some products are unavailable. Write down those expected conditions beside the expansion proposal.
A useful discussion can then ask which products have stock, which have fulfilment capacity and which serve the current trading objective. The campaign team can describe the likely invitation, while merchandising and operations confirm whether the proposed demand is useful.
That coordination prevents an average revenue result from standing in for a complete expansion plan. The budget decision concerns the next set of orders the business is ready to fulfil, with a clear view of the costs and conditions attached to that mix.
Make the target describe the intended trade
Put the headline revenue objective beside the relevant mix and business conditions. This gives the team a clearer account of what a successful campaign should produce.
The result is a more useful budget conversation: which orders the business wants, what it can fulfil and how advertising can support that trade. Revenue remains part of the answer, with the products behind it made visible.
A thought worth keeping?